
A War Front That Moves Markets
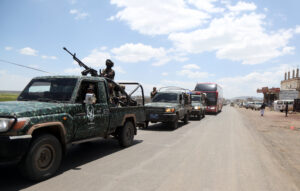
Brent crude is trading around $100 a barrel, and the number keeping traders anchored to that level is not an OPEC decision or a demand forecast – it is the ongoing military conflict in Yemen, where Houthi forces aligned with Iran have been fighting for control of strategic territory near the Red Sea. The recapture of the port city of Mokha by Yemeni forces in a major counteroffensive has done little to calm markets, because the underlying question is not who holds the city today but how far the fighting spreads tomorrow.
Oil markets have spent years pricing in Middle East risk as background noise, a persistent discount that traders learn to ignore. What is different now is the geography. The Red Sea is not incidental to global oil flows – it is one of the arteries through which millions of barrels move each day, and military activity anywhere near its shipping lanes forces buyers, sellers, and insurers to run calculations they would rather not be running.
What Mokha Means for Supply Routes
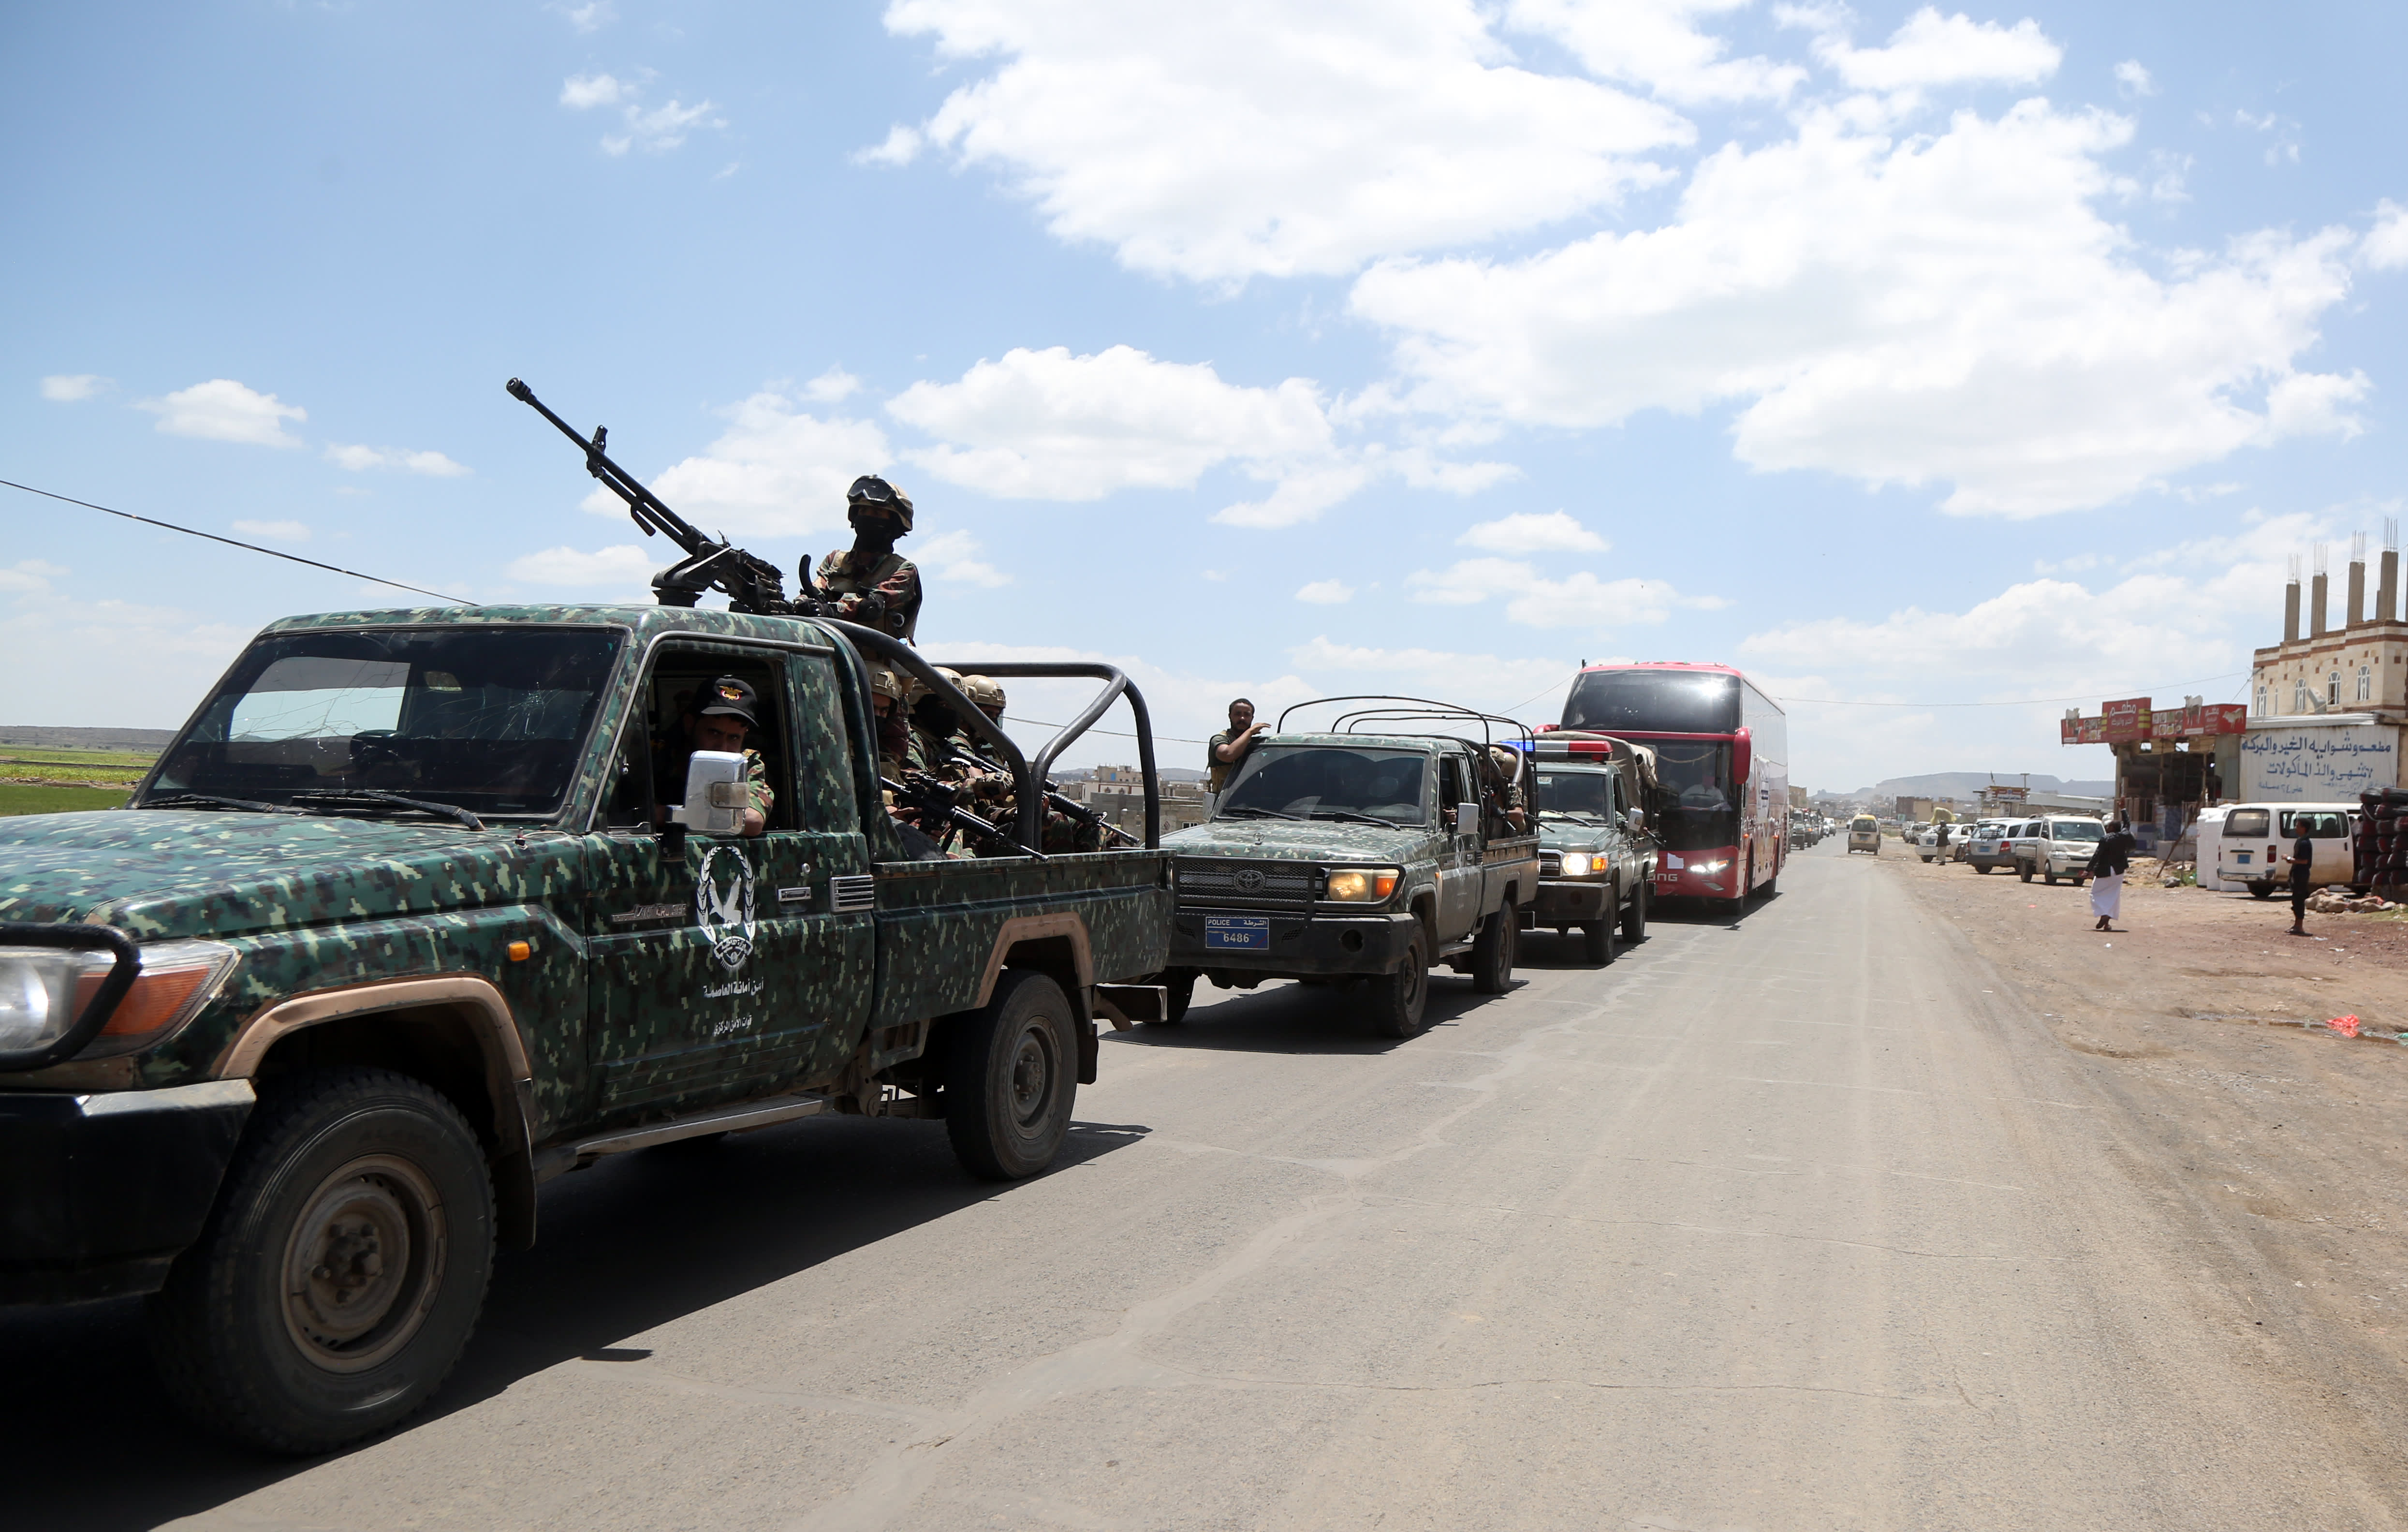
Mokha sits on Yemen’s western coast, directly facing the Bab el-Mandeb strait – the narrow chokepoint connecting the Red Sea to the Gulf of Aden. Any military force with a presence near that corridor has the potential to threaten commercial shipping, whether through direct attacks, mining operations, or the kind of unpredictable disruption that pushes insurance premiums sharply higher. Houthi forces have demonstrated both the will and the capability to target vessels in these waters, a pattern that established itself well before the current counteroffensive.
Yemeni forces reclaiming Mokha removes one pressure point but does not resolve the broader strategic picture. Iran-backed Houthi fighters retain significant territorial and military capacity elsewhere in the country, and a battlefield setback does not automatically translate into reduced threat to maritime traffic. Shipping companies and energy traders are watching the next moves carefully, not celebrating a single city changing hands.
The market’s reaction – Brent holding near $100 rather than selling off on the counteroffensive news – reflects exactly that calculation. Price at this level is embedding a risk premium for continued escalation, and that premium does not dissolve until there is evidence the conflict is genuinely contracting rather than shifting location.
The $100 Number and What It Signals
Brent at $100 a barrel is a psychologically loaded price. It is the level that historically triggers demand destruction conversations, forces central banks to reassess inflation trajectories, and starts appearing in household energy bills in ways that generate political pressure. At the same time, it is the level that keeps high-cost producers – offshore deepwater, Canadian oil sands, some U.S. shale – comfortably in the money, which means production investment decisions made today will shape supply curves two and three years from now.
The risk of further escalation, as framed by traders watching the Yemen situation, is not limited to physical supply disruption. Even a period of elevated uncertainty without actual pipeline or tanker damage is enough to keep the risk premium alive. Insurers repricing war-risk coverage for Red Sea transits effectively raises the delivered cost of oil moving through that corridor, which feeds into spot prices regardless of whether a single barrel is delayed.
The countries most exposed to a sustained $100 environment differ sharply depending on which side of the trade they sit on. Energy-importing economies in Asia – particularly those heavily dependent on Middle Eastern crude moving through the Red Sea – face the most direct pass-through to industrial costs and consumer prices. Gulf producers, by contrast, are looking at revenue windfalls that ease fiscal pressures built up during lower-price periods. Saudi Arabia, which has its own complicated relationship with the Yemen conflict as a former direct military participant, is now watching oil prices do something its own production policy has been trying to engineer for much of the past two years.
There is a further complication layered beneath the supply-route anxiety. If the Yemen counteroffensive represents a broader shift in the regional balance of power between Saudi-aligned forces and Iranian-backed ones, the political fallout extends well beyond Yemen’s borders. Iran’s own oil exports – still moving through separate channels despite sanctions – become a factor in how markets price the possibility of direct confrontation between major regional actors. That is a scenario oil markets have not had to fully price since before the Iran nuclear deal era, and the intellectual infrastructure for doing so is not as sharp as it once was.
Where the Risk Goes From Here
Oil market analysts tracking the Yemen situation are not modeling a single clean scenario. The range of outcomes runs from a relatively contained conflict that keeps Brent in the $95-to-$105 band for several months, to escalation that pulls in additional regional actors and drives prices to levels not seen since the supply shocks of the early part of this decade. Neither extreme is priced as a certainty; the current $100 level represents the market’s best guess at a probability-weighted middle.
What would push that price lower is evidence of genuine de-escalation – ceasefire talks gaining traction, Iranian pressure on Houthi forces easing, or shipping companies reporting reduced threat assessments in the Bab el-Mandeb corridor. What would push it higher is almost anything that suggests the Yemeni counteroffensive triggers a Houthi response targeting oil infrastructure directly, whether in Yemen, Saudi Arabia, or at sea.
For energy companies and the traders who move their product, the calculation is straightforward even if the outcome is not: the Red Sea is too important to treat as a side story, and Brent at $100 is the market saying so in the clearest language it has.
The last time insurance premiums for Red Sea transits spiked to comparable levels, several major shipping operators quietly began rerouting around the Cape of Good Hope – adding days to delivery schedules and hundreds of thousands of dollars per voyage in fuel costs. That option is always on the table. But with oil at $100, every detour has a price of its own.