

Chinese President Xi Jinping, who in May asked U.S. President Donald Trump directly whether the two countries could avoid destructive rivalry, now appears to have reached his own answer: yes.

A Question That Set the Stage
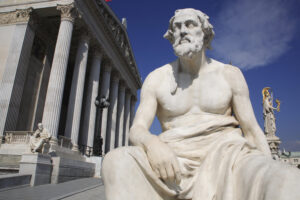
The framing Xi used – the “Thucydides Trap” – comes from the ancient Greek historian’s account of how Sparta’s fear of a rising Athens made war between them nearly inevitable. Harvard political scientist Graham Allison later applied the concept to great-power competition, arguing that when a rising power threatens an established one, conflict tends to follow. Xi’s invocation of it was not academic. It was a signal about how Beijing reads the current moment with Washington.
That Xi raised the question directly with Trump in May is itself significant. Heads of state rarely float theoretical frameworks in bilateral conversations unless those frameworks are doing real political work. In this case, the framing allowed Xi to acknowledge the structural risk of U.S.-China competition without conceding that conflict is determined – and to invite Trump into a shared narrative where both sides choose a different outcome.
The shift in Xi’s apparent confidence since that May exchange also carries weight. Moving from posing a question to projecting an answer suggests Beijing believes something has changed in the relationship’s trajectory – whether in the tone of negotiations, the behavior of markets, or the internal calculations of the Trump administration regarding how far confrontation can go before it starts costing more than it gains.
For businesses operating across both economies, the psychological temperature between Xi and Trump matters as much as any specific policy. Tariff schedules and export controls are the mechanism, but executive confidence – or its absence – is what determines whether multinationals plan for integration or fragmentation over the next decade.
What “Avoiding the Trap” Actually Means for Trade and Capital
The Thucydides Trap, as a business concern, is not primarily about military conflict. It is about the economic decoupling that precedes or accompanies strategic rivalry – supply chain separation, technology export restrictions, financial market segmentation, and the growing cost of operating in both jurisdictions simultaneously. When Xi asks whether the U.S. and China can avoid destructive rivalry, the word “destructive” is doing a lot of work. Both governments have already accepted a significant level of rivalry. The question is whether it stays managed.
Xi’s apparent optimism, reported in September, comes at a moment when the economic consequences of sustained confrontation are increasingly visible on both sides. U.S. companies with deep China exposure have spent years restructuring supply chains under pressure from tariffs that began in Trump’s first term and were largely maintained under the Biden administration. Chinese exporters, meanwhile, have faced a strengthening yuan that compounds the damage from external demand uncertainty – a pressure point that has pushed Chinese banks into active hedging strategies to protect export revenues.

The commercial logic for de-escalation is straightforward even if the political logic is not. China remains one of the largest consumer markets in the world, and American brands from automotive to luxury goods to technology have built revenue models that depend on access to it. At the same time, Chinese manufacturers depend on U.S. and allied markets for the export volumes that sustain employment and industrial utilization rates. Full decoupling would require both sides to absorb costs that neither has fully priced in.
What Xi’s framing suggests – and what the May conversation with Trump appears to have reinforced – is that Beijing is willing to pursue competitive coexistence rather than zero-sum displacement. That is a meaningful distinction for capital allocation. An environment where the two powers compete intensely but within recognized limits supports investment strategies that maintain dual exposure. An environment trending toward the Thucydides outcome – actual rupture – demands a very different portfolio.
The September signals from Xi do not resolve that uncertainty, but they shift the probability distribution. Markets, which spent much of 2025 pricing tail risk on U.S.-China confrontation, will need to recalibrate if Beijing’s confidence proves well-founded and is met with any reciprocal shift in Washington’s posture. The Dow and S&P 500 have already shown sensitivity to U.S.-China diplomatic signals, with futures markets reacting to news of engagement or breakdown within hours of reports emerging.
Trump’s Side of the Equation
Xi can project optimism, but the Thucydides Trap requires two parties to avoid it. Trump’s approach to China has been consistently transactional – focused on specific grievances around trade balances, technology transfer, and manufacturing jobs rather than on grand strategic frameworks. Whether that transactional orientation makes conflict less likely or more unpredictable is genuinely unclear. A president who treats every issue as a negotiation may be easier to manage than one pursuing ideological containment, or harder, depending on what triggers the next demand.
What Xi’s question in May and his apparent answer in September both point toward is a Chinese leadership that has decided engagement – even difficult, asymmetric engagement – is preferable to the alternative. Whether the Trump administration has reached the same conclusion, and on what terms, is the detail that will actually determine whether the trap gets avoided or simply postponed.